
تقرير الكربون الأسود الأسبوعي: تراجع السوق
Black Carbon Market Analysis
1.1 Black Carbon Market Price Analysis
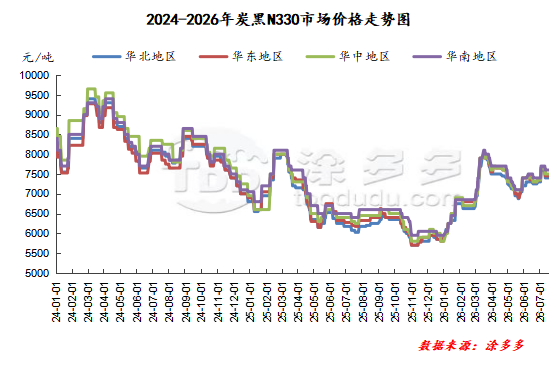
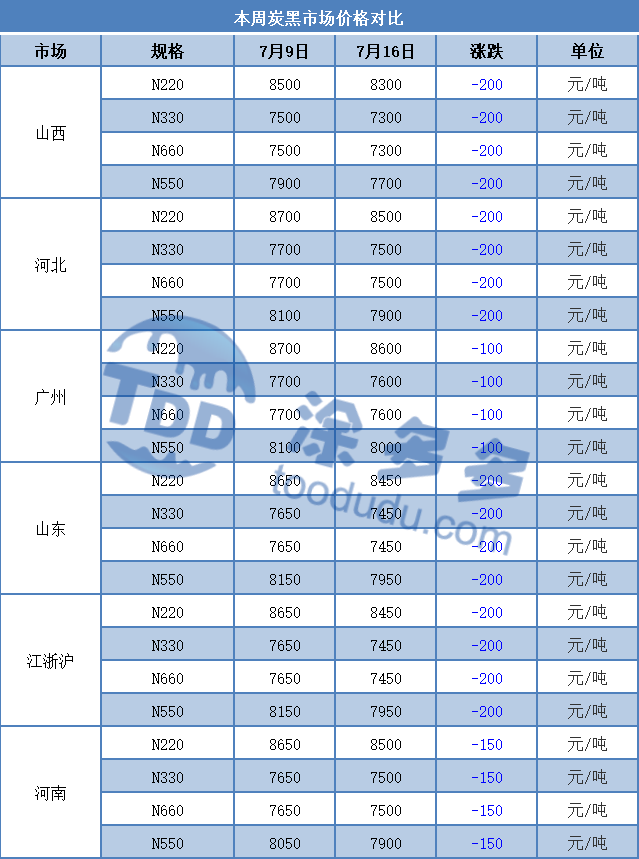
This week, domestic black carbon prices showed a significant downward trend. As of Thursday, prices were as follows: Shandong 7450 yuan/ton; Shanxi 7300 yuan/ton; Hebei 7500 yuan/ton; Guangzhou 7600 yuan/ton; and Zhejiang 7450 yuan/ton. The prices of new orders for raw tar material further declined this week. Although the prices of deep-processed small products and industrial naphthalene rose sharply due to the surge in crude oil prices, the main end products such as coal tar and black carbon remained weak.
Therefore, negative factors continued to dominate the market, and tar prices kept falling. Downstream buyers mainly waited for price drops, inquiries decreased, and actual transactions were limited. Negotiations between upstream and downstream players were ongoing, and the black carbon market is expected to remain weak in the short term.
1.2 Black Carbon Market Index Analysis
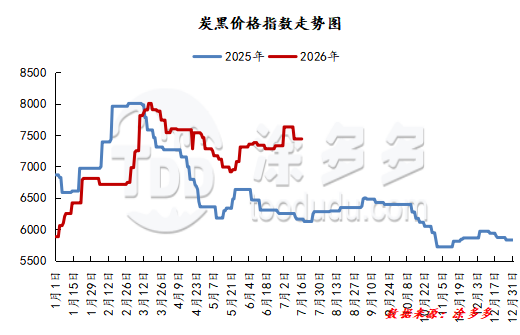
According to data from TuDuoDuo, as of July 16, the black carbon price index was 7438, a decrease of 191.5 from the previous period.
2. Raw Material Market Analysis
2.1 Weekly Average Tar Price Analysis
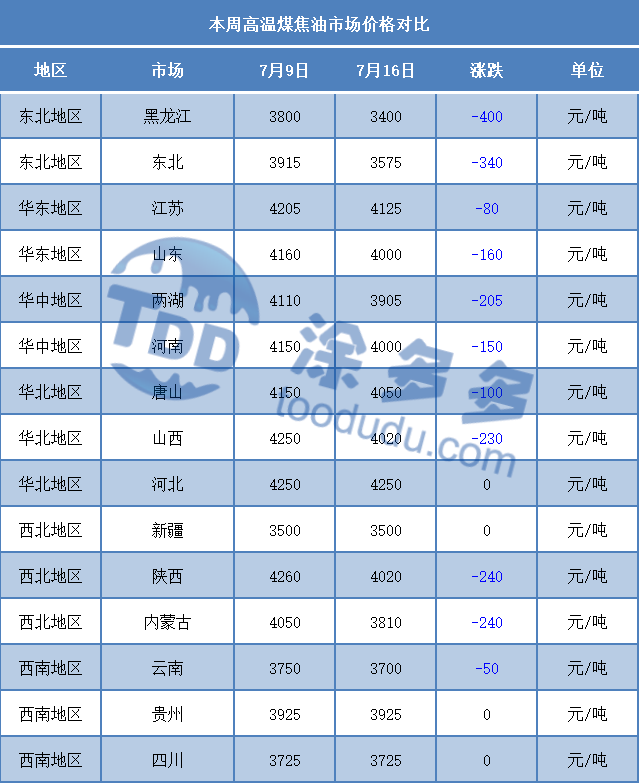
This period saw a downward trend in the domestic high-temperature tar market. At the beginning of the week, tar prices remained relatively stable, but by the end of the week, new orders for high-temperature tar were issued, leading to a significant price drop.
Despite the sharp rise in prices of deep-processed small products and industrial naphthalene, the prices of main end products such as coal tar, black carbon, and anthracene oil all trended downward. Downstream factories showed strong selling pressure, and the market is expected to remain in a predominantly downward trend in the short term.
2.2 Weekly Average Anthracene Oil Price Analysis
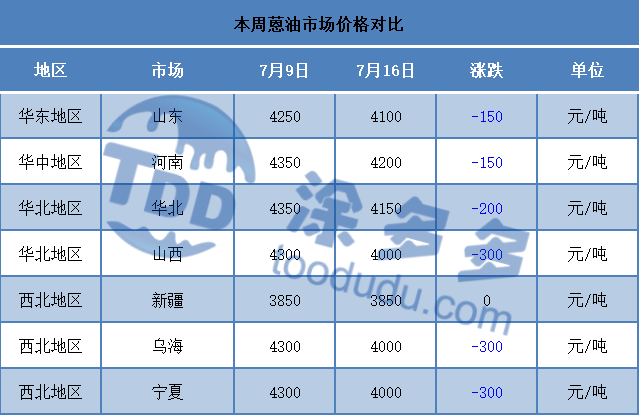
This period saw a decline in some prices in the domestic anthracene oil market. With the issuance of new orders for high-temperature tar, the overall price showed a broad decline. Anthracene oil manufacturers were very cautious in their pricing and showed little willingness to significantly lower prices. Downstream users also adopted a wait-and-see approach due to weak demand. The anthracene oil market is expected to remain at a low level in the short term.
3. Black Carbon Market Forecast
Looking at the next cycle, the raw material market is expected to see a broader price decline, negatively impacting costs. Negotiations for new orders are also expected to decrease, and downstream inquiries are expected to weaken as buyers adopt a wait-and-see approach. Further reductions in new order prices are anticipated.
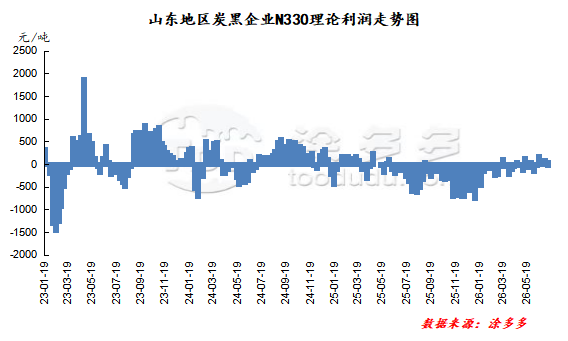
4. Black Carbon N330 Industry Profit Analysis
For example, in Shandong, the decline in new order prices for raw tar material widened, providing cost advantages to the market. However, negotiations for new black carbon orders stalled. Despite the announced price reductions, downstream buyers continued to push for lower prices, and actual orders remained under negotiation. Therefore, theoretically, the market is currently in a profitable position. As of now, the theoretical weekly profit for the black carbon industry is 45 yuan/ton.
5. Market Operating Rate Statistics This Week
5.1 Black Carbon Market Operating Rate Analysis
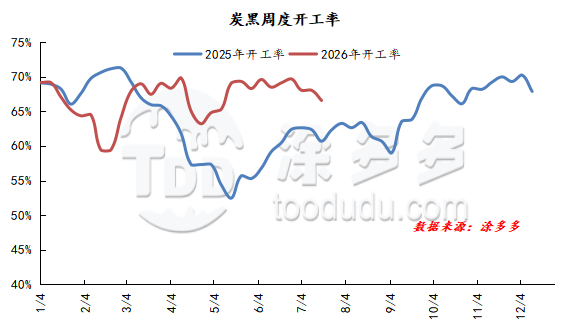
The operating rate of typical enterprises in the domestic black carbon market was 67%. The operating rate of typical enterprises in the domestic black carbon market slightly decreased. Due to recent pressure on black carbon shipments and inventory accumulation, some large factories in the region reduced their operating rates. At the same time, a factory in East China was still under maintenance. Overall, the operating rate of black carbon enterprises decreased this week.
5.2 Downstream Market Operating Rate Analysis
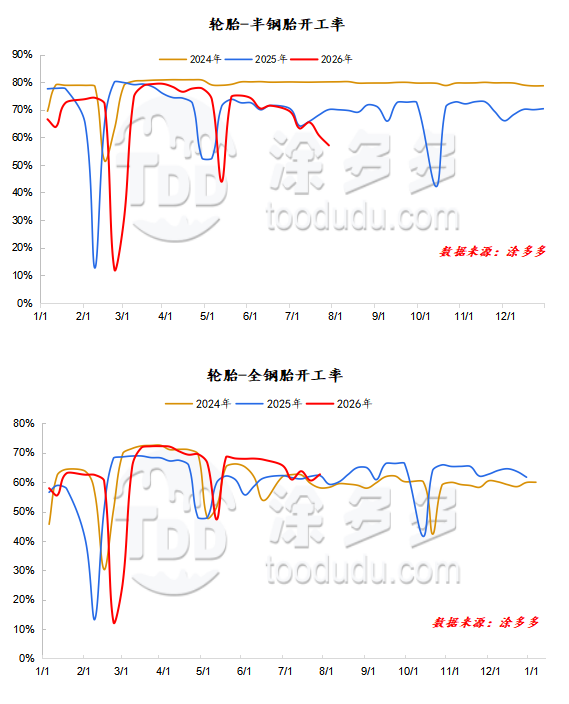
The operating rate of semi-steel tires in China was 57%. The operating rate of full-steel tires in China was 63%.
This week, the tire operating rate showed variation. Some typical enterprises in the semi-steel tire sector had scheduled maintenance for 3-5 days, leading to a decrease in capacity utilization rates for typical enterprises. Regarding full-steel tires, some typical enterprises that had previously undergone maintenance gradually resumed production at normal levels, leading to a recovery in capacity utilization rates for typical full-steel tire enterprises.
Our platform connects hundreds of certified Chinese chemical suppliers with buyers worldwide, promoting transparent transactions, better business opportunities, and high-value partnerships. Whether you're looking for bulk commodities, specialty chemicals, or customized procurement services, TDD-Global is your trusted choice.









